Give AxonX a Star on GitHub! ↗
AGENT-NATIVE QUANT HARNESS
Quantitative research.
Built with Agents.
An agent-native harness for quantitative code development, experiment execution, and result analysis. Use your prompt and AxonX Skill with an Agent to improve Qlib Alpha158-based plugins or develop new research plugins.

Latest Updates
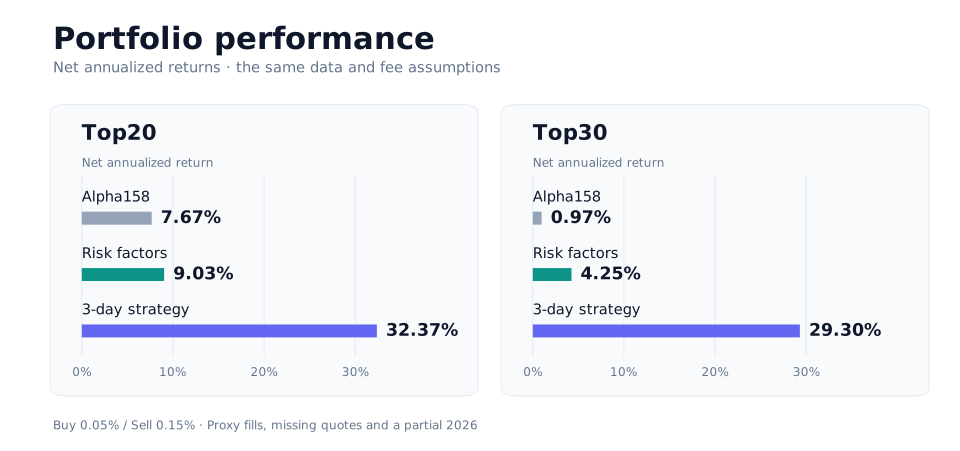
- Qlib Alpha158 enhancement experiments: the risk-factor model and rank-retention strategy report Top20 net annualized return improvements of +1.36 pp and +24.70 pp, respectively, over the adapted baseline (pp = percentage points). → Results and evidence limits
- Studio Playground: explore Tasks and research charts with simulated data and execution. → Try Playground
01 / GET STARTED
Run your first task
Submit, follow, and inspect a built-in demo task.
↗02 / AGENT DEVELOPMENT
Develop with an Agent
Prepare source and tools; use the Skill and a research prompt to develop plugins.
↗03 / RESEARCH
Build a research workflow
Run a baseline, develop plugins, and evaluate features, models, and portfolio policies.
↗01 / AXONX STUDIO
See your research unfold.
From task execution to result interpretation, inspect your research in one workspace.
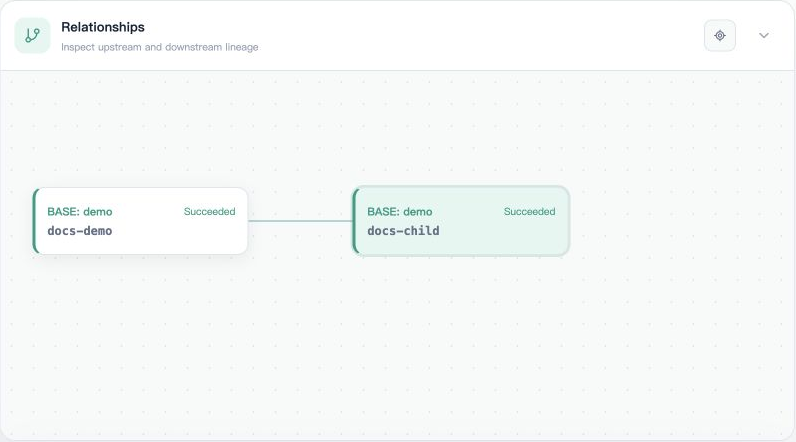
Inspect execution records and trace upstream artifacts.
Read the guide ↗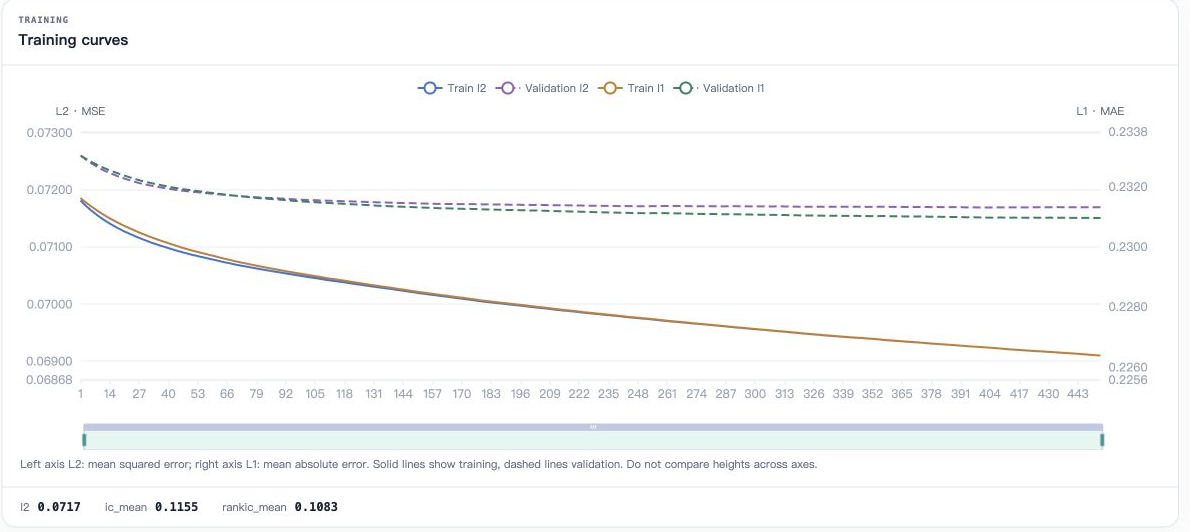
Inspect the evidence, from configuration to validation curves.
Read the guide ↗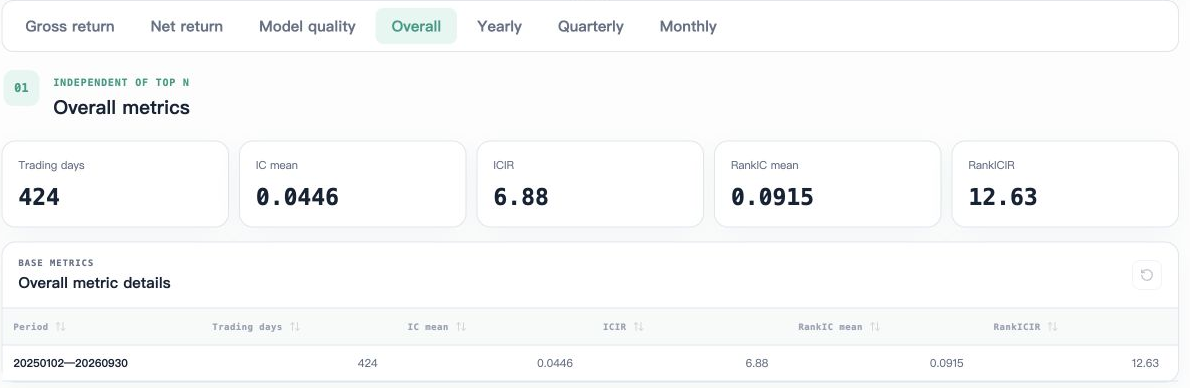
Read returns, costs, and quality together.
Read the guide ↗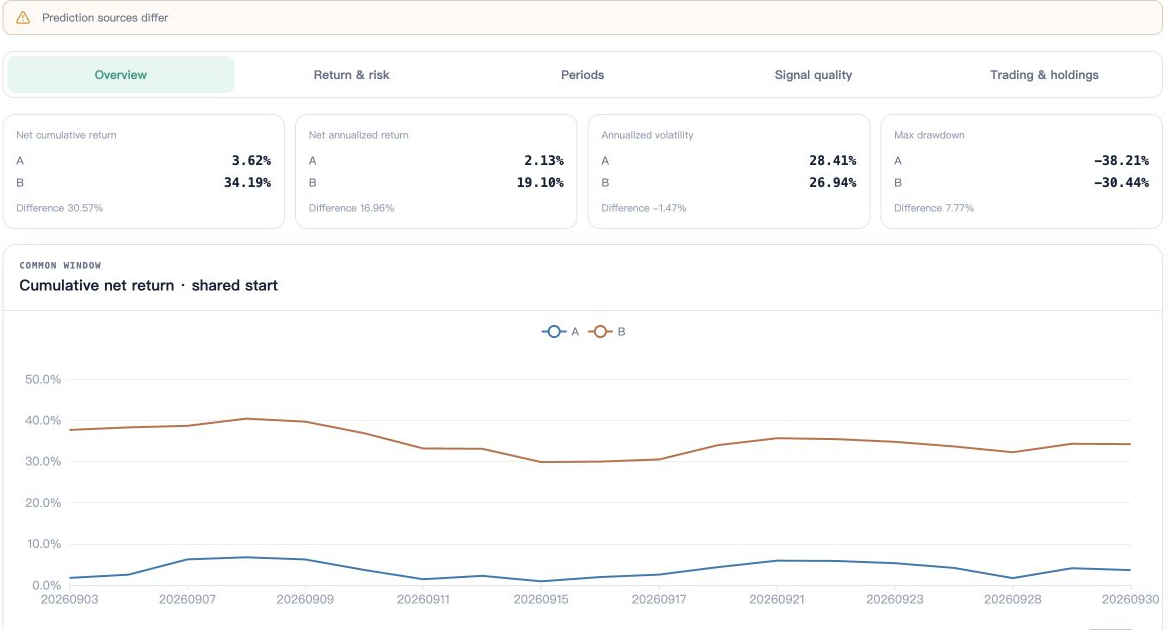
Understand strategy differences over a shared period.
Read the guide ↗02 / HARNESS CORE
Flexible research. Grounded execution.
PLUGIN ↗
Research, independently extensible
Package algorithms and tasks as plugins with explicit input and output contracts.
TASK ↗
A record of every run
Keep status, logs, parameters, and artifacts in one task workspace.
MACHINE ↗
Multiple machines, one entry point
Access remote tasks, machine resources, and research results through a shared interface.
JOB API ↗
Studio, CLI, and agents connected
Share Job interfaces and workspace records to iterate on research evidence.
03 / CONTINUE YOUR RESEARCH
Continue by goal.
AGENT ↗
Research with an agent
Develop or improve research plugins, run Tasks, inspect results, and iterate.
EXPERIMENT ↗
Design inspectable experiments
Fix controls, screen candidates, then confirm independently.
OPERATIONS ↗
Manage execution environments
Connect remote machines and maintain tasks, files, and services.
DEVELOP ↗
Extend research capabilities
Build plugins using Task contracts and framework extension points.
04 / AGENT RESEARCH CASE
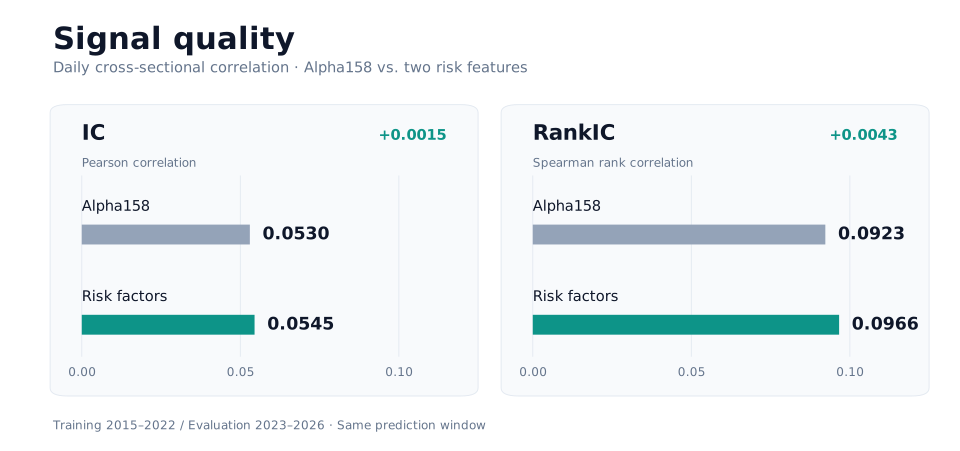
Improving Qlib Alpha158 with factors and portfolio policies
Top20 net annualized returns are 7.67%, 9.03%, and 32.37% for Alpha158, two added risk factors, and 3-day rank retention, with buy/sell fees of 0.05%/0.15%. Base and factor models use different feature_fraction settings; market data is incomplete and there is no independent confirmation window.
05 / BUILD YOUR RESEARCH LOOP
Start with one Task.
The built-in demo needs no external data or model credentials.